UK Tools

Finance & Money

UK Stamp Duty Calculator

On a £300,000 home in England or Northern Ireland you pay £5,000 stamp duty (1.67%), or nothing as a first-time buyer. As a second home it is £20,000. Enter your own price below.

Last updated: · Rates checked against official sources: · Written and checked by Aivora Digital

Stamp duty is one of the biggest upfront costs when you buy a home in the UK, and the tax depends on where the property is: Stamp Duty Land Tax (SDLT) in England and Northern Ireland, Land and Buildings Transaction Tax (LBTT) in Scotland and Land Transaction Tax (LTT) in Wales.

Choose the nation, enter the price and pick your buyer type. You get the total, the effective rate and a band-by-band breakdown you can copy for your solicitor or budget spreadsheet. Tick the non-UK resident box if you have spent fewer than 183 days in the UK in the 12 months before buying in England or Northern Ireland.

The rates below were checked against GOV.UK, Revenue Scotland and the Welsh Revenue Authority on 28 October 2026. England’s current bands have applied since 1 April 2025, Scotland’s since 1 April 2021 (with an 8% supplement on additional homes since 5 December 2024), and Wales’s main rates since 10 October 2022.

For the full explanation, read How stamp duty works when you buy a home in the UK, How UK mortgage payments are calculated, How UK Inheritance Tax is calculated (2026/27), How UK Council Tax bands and bills are calculated or How UK Capital Gains Tax is calculated (2026/27).

Work out the stamp duty on a purchase

Residential rates checked 28 October 2026

England & NI: 0% to £125,000, 2% to £250,000, 5% to £925,000, 10% to £1.5m, 12% above. First-time buyers pay 0% to £300,000 and 5% to £500,000 if the price is £500,000 or less. Second homes add 5% to every band. Scotland (LBTT) starts at £145,000 and Wales (LTT) at £225,000.
Examples:

Additional = you will own more than one home after buying

SDLT (England & Northern Ireland)

Estimated tax due£7,500.00
Purchase price£350,000.00
Effective rate2.14%
Band breakdown
SliceRateTax
£0 – £125,0000.0%£0.00
£125,000 – £250,0002.0%£2,500.00
£250,000 – £350,0005.0%£5,000.00

Covers residential purchases by individuals. Shared ownership, company purchases, leases with rent above £125,000 and non-residential property have their own rules, so check those with HMRC, Revenue Scotland, the Welsh Revenue Authority or your conveyancer.

Worked examples

Examples you can read without entering anything. Use your own figures for a personal estimate.

England & NI · £300,000 · standard residential SDLT

Your only home after the purchase, and you have owned a home before.

Inputs

Location
England & Northern Ireland
Purchase price
£300,000
Buyer type
Standard (main residence)

Results

SDLT
£5,000
Effective rate
1.67%

0% on the first £125,000 (£0), 2% on the next £125,000 (£2,500) and 5% on the last £50,000 (£2,500).

England & NI · £400,000 · first-time buyer

Everyone buying is a first-time buyer and the price is £500,000 or less.

Inputs

Location
England & Northern Ireland
Purchase price
£400,000
Buyer type
First-time buyer

Results

SDLT
£5,000
Saving against standard rates
£5,000

0% up to £300,000, then 5% on the £100,000 above it. At standard rates the same home costs £10,000.

England & NI · £650,000 · standard residential

A common price in London and the South East. London uses the same rates as the rest of England.

Inputs

Location
England & Northern Ireland
Purchase price
£650,000
Buyer type
Standard (main residence)

Results

SDLT
£22,500
Effective rate
3.46%

£0 on the first £125,000, £2,500 on the next £125,000 and 5% of £400,000 (£20,000). A first-time buyer pays the same, because relief stops above £500,000.

England & NI · £250,000 · second home or buy-to-let

You will own two homes at the end of the day you complete.

Inputs

Location
England & Northern Ireland
Purchase price
£250,000
Buyer type
Additional property

Results

SDLT
£15,000
Extra over a main home
£12,500

5% on the first £125,000 (£6,250) and 7% on the next £125,000 (£8,750). The extra 5 points apply to the whole price.

Scotland · £300,000 · LBTT, standard and first-time buyer

Revenue Scotland’s bands start at £145,000; first-time buyers get a £175,000 nil band.

Inputs

Location
Scotland
Purchase price
£300,000

Results

LBTT (standard)
£4,600
LBTT (first-time buyer)
£4,000
LBTT + 8% ADS (additional home)
£28,600

2% of £105,000 (£2,100) plus 5% of £50,000 (£2,500). First-time buyer relief saves at most £600. ADS is 8% of the full price (£24,000).

Wales · £300,000 · LTT, main home and higher rates

Wales has no first-time buyer relief, but tax starts at £225,000.

Inputs

Location
Wales
Purchase price
£300,000

Results

LTT (main home)
£4,500
LTT (higher rates)
£19,950

Main rates: 6% of the £75,000 above £225,000. Higher rates: 5% to £180,000 (£9,000), 8.5% to £250,000 (£5,950) and 10% on £50,000 (£5,000).

Stamp duty rates in England and Northern Ireland

Stamp Duty Land Tax is charged in slices. You pay nothing on the first £125,000, 2% on the portion from £125,001 to £250,000, 5% from £250,001 to £925,000, 10% from £925,001 to £1.5 million and 12% on anything above. These bands have applied since 1 April 2025, when the temporary £250,000 starting threshold ended.

First-time buyers pay nothing up to £300,000 and 5% on the portion from £300,001 to £500,000. If the price is over £500,000 the relief is lost completely and the whole price goes through the normal bands. Everyone buying must be a first-time buyer, and the home must be your main residence.

If you will own more than one residential property worth £40,000 or more at the end of the day you complete, you usually pay 5 percentage points on top of every band: 5%, 7%, 10%, 15% and 17%. Buyers who were in the UK for fewer than 183 days in the 12 months before the purchase pay a further 2% on every band, on top of any other rates.

You or your conveyancer must send the SDLT return and pay within 14 days of completion. Use the mortgage calculator to see the monthly cost of the loan and the Council Tax band helper for the yearly bill once you move in.

Stamp Duty Land Tax on residential purchases in England and Northern Ireland by UK residents, from 1 April 2025. Non-UK residents add 2% of the price.
PriceStandardFirst-time buyerAdditional property
£150,000£500£0£8,000
£200,000£1,500£0£11,500
£250,000£2,500£0£15,000
£300,000£5,000£0£20,000
£325,000£6,250£1,250£22,500
£350,000£7,500£2,500£25,000
£400,000£10,000£5,000£30,000
£450,000£12,500£7,500£35,000
£500,000£15,000£10,000£40,000
£600,000£20,000£20,000£50,000
£650,000£22,500£22,500£55,000
£750,000£27,500£27,500£65,000
£1,000,000£43,750£43,750£93,750
£1,500,000£93,750£93,750£168,750

How to work out stamp duty by hand

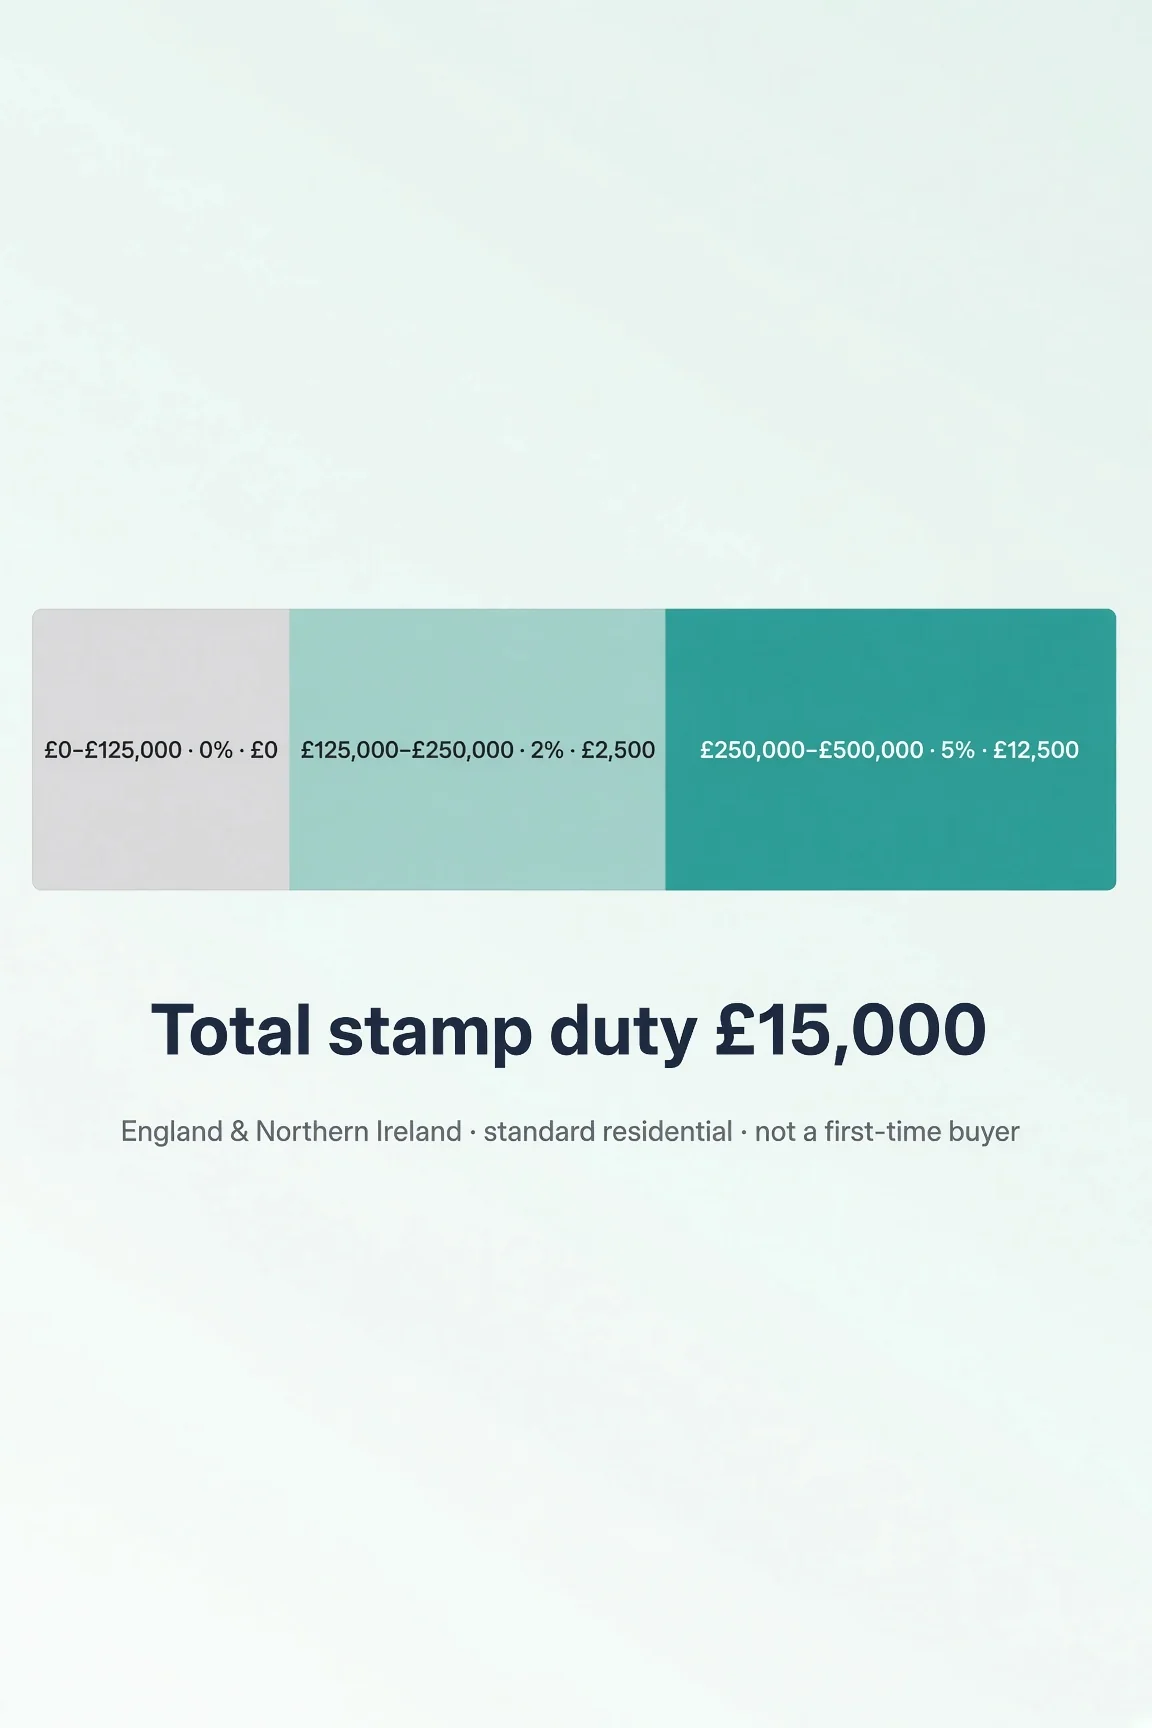
Stacked bar showing £500,000 stamp duty: £0 on the first £125,000, £2,500 at 2%, £12,500 at 5%
A £500,000 home: £0 on the first £125,000, 2% of the next £125,000, 5% of the rest — £15,000 in total.

Split the price at each band edge, multiply each slice by its rate and add the results. Take a £500,000 home bought by someone who has owned before: £0 on the first £125,000, 2% of £125,000 is £2,500, and 5% of the remaining £250,000 is £12,500. The total is £15,000, an effective rate of 3%.

For the same £500,000 home a first-time buyer pays 5% of the £200,000 above £300,000, which is £10,000. GOV.UK uses exactly this example. As a second home, the rates become 5%, 7% and 10%: £6,250 + £8,750 + £25,000 = £40,000.

A quick check for standard SDLT between £250,000 and £925,000 is 5% of the price minus £10,000. For £400,000 that is £20,000 − £10,000 = £10,000, which matches the table.

Second home and buy-to-let stamp duty

The higher rates apply to second homes, buy-to-lets and holiday lets, and to the whole price rather than only the slice above a threshold. GOV.UK’s own example is a £300,000 additional home: 5% on the first £125,000 (£6,250), 7% on the next £125,000 (£8,750) and 10% on the last £50,000 (£5,000), a total of £20,000. As your only home the same property costs £5,000.

Married couples and civil partners are treated as one unit, so if either of you already owns a home the higher rates usually apply even when only one of you is buying. Property worth less than £40,000, caravans and houseboats are not counted.

If you buy a new main home before selling the old one, you pay the higher rates on completion and can claim the extra back if you sell the previous main home within 36 months. HMRC usually pays a refund within 15 working days of receiving the claim. Selling a second home later can bring a Capital Gains Tax bill, which you can estimate with the Capital Gains Tax calculator.

Scotland (LBTT) and Wales (LTT)

Scotland charges Land and Buildings Transaction Tax: 0% up to £145,000, 2% to £250,000, 5% to £325,000, 10% to £750,000 and 12% above. First-time buyers get a £175,000 nil band, which saves up to £600. The Additional Dwelling Supplement adds 8% of the full price on second homes and buy-to-lets where the price is £40,000 or more. On a £235,000 home Revenue Scotland’s example gives £1,800; on £875,000 it is £63,350.

Wales charges Land Transaction Tax: 0% up to £225,000, 6% to £400,000, 7.5% to £750,000, 10% to £1.5 million and 12% above. There is no separate first-time buyer relief, but the higher starting threshold means a £225,000 first home pays nothing. Higher rates for additional homes start at 5% and rise to 17%; the Welsh Revenue Authority’s example of a £260,000 second home costs £15,950.

The tax follows the location of the property, not where you live. A Glasgow buyer purchasing in Cardiff pays LTT, and a London buyer purchasing in Edinburgh pays LBTT.

Tax on the same prices in each nation, for a buyer who has owned a home before.
PriceEngland & NI (SDLT)Scotland (LBTT)Wales (LTT)
£200,000£1,500£1,100£0
£250,000£2,500£2,100£1,500
£300,000£5,000£4,600£4,500
£400,000£10,000£13,350£10,500
£500,000£15,000£23,350£18,000
£750,000£27,500£48,350£36,750

Common stamp duty mistakes

Treating the first-time buyer limit as a threshold rather than a cliff. A first-time buyer pays £10,000 on a £500,000 home but £15,500 on a £510,000 one, because above £500,000 the relief disappears and the whole price is taxed at standard rates.

Using an old calculator. Between 23 September 2022 and 31 March 2025 nobody paid SDLT on the first £250,000 and first-time buyers paid nothing up to £425,000, so a £300,000 purchase in that period cost £2,500 rather than today’s £5,000. If you are checking what you paid on an earlier purchase, use the rates for the date you completed.

Forgetting that the 5% surcharge applies to the whole price. On a £400,000 buy-to-let the bill is £30,000, not the £10,000 standard charge plus 5% of the slice above £250,000.

Assuming the deadline is flexible. SDLT returns and payment are due within 14 days of completion, and HMRC can charge penalties and interest on late returns.

Stamp duty in earlier years

From 4 December 2014 to 7 July 2020 the standard SDLT bands were the same as today: 0% to £125,000, 2% to £250,000, 5% to £925,000, 10% to £1.5 million and 12% above. First-time buyer relief, 0% to £300,000 and 5% to £500,000, started on 22 November 2017. The surcharge on additional homes was 3% from 1 April 2016 to 30 October 2024 and has been 5% since 31 October 2024.

So a £300,000 home bought in 2018 or 2019 by someone who had owned before cost £5,000, the same as now, while the same purchase as a second home cost £14,000 then against £20,000 today. GOV.UK publishes the full table for each period if you need to check an older purchase.

Official sources & further reading

Check rates, bands and eligibility on these official pages before you rely on a figure.

Frequently asked questions

How much stamp duty will I pay?
In England and Northern Ireland, nothing on the first £125,000, 2% on the next £125,000 and 5% from £250,001 to £925,000. That works out at £500 on £150,000, £5,000 on £300,000, £10,000 on £400,000 and £15,000 on £500,000. First-time buyers pay nothing up to £300,000, and second homes cost 5 points more on every band.
How much stamp duty do I pay on £150,000?
£500 in England or Northern Ireland if it will be your only home (2% of the £25,000 above £125,000). A first-time buyer pays nothing. As a second home it is £8,000. In Scotland the standard LBTT is £100, and in Wales there is no LTT on a main home at this price.
How much stamp duty on a £325,000 house?
£6,250 at standard rates in England and Northern Ireland: £2,500 on the slice from £125,001 to £250,000 and £3,750 on the last £75,000. A first-time buyer pays £1,250 (5% of £25,000), and a second-home buyer pays £22,500.
How much stamp duty on £500,000?
£15,000 at standard rates, £10,000 for first-time buyers and £40,000 for an additional property in England and Northern Ireland. £500,000 is the highest price at which first-time buyer relief still applies.
How much stamp duty on a £750,000 house?
£27,500 in England and Northern Ireland, whether or not you are a first-time buyer, because relief stops above £500,000. As a second home it is £65,000. In Scotland the standard LBTT is £48,350 and in Wales the LTT on a main home is £36,750.
Do I pay stamp duty on a second home?
Yes, if you will own more than one residential property worth £40,000 or more. In England and Northern Ireland the higher rates add 5 percentage points to every band across the whole price, so a £250,000 second home costs £15,000 rather than £2,500, and a £300,000 one costs £20,000.
Is stamp duty different in London?
No. London uses the same Stamp Duty Land Tax rates as the rest of England and Northern Ireland. A £650,000 home costs £22,500 whether it is in Camden or Carlisle. Bills are bigger in London only because prices are higher.
What is the difference between SDLT, LBTT and LTT?
They are the property purchase taxes of different parts of the UK. SDLT applies in England and Northern Ireland and is collected by HMRC. LBTT applies in Scotland and is collected by Revenue Scotland. LTT applies in Wales and is collected by the Welsh Revenue Authority. Each has its own bands, and the one you pay depends on where the property is.
Can I get a stamp duty refund?
Usually, if you paid the higher rates on a new main home and then sell your previous main home within 36 months, or if you paid the non-UK resident surcharge and later become UK resident for SDLT purposes. You can also claim back an overpayment from a mistake or a relief you forgot to claim. HMRC usually pays within 15 working days of receiving the claim.
How much stamp duty did I pay on my house?
Your completion statement from your solicitor shows the exact amount. To work it out yourself, use the rates for the date you completed: between 23 September 2022 and 31 March 2025 the nil band was £250,000 (£425,000 for first-time buyers), so most purchases in that period cost less than they would today.
Does this cover commercial property?
No. It covers residential purchases. Non-residential and mixed-use property in England and Northern Ireland has its own bands, starting at £150,000.
When is stamp duty payable?
In England and Northern Ireland the SDLT return and payment are due within 14 days of completion. Your solicitor or conveyancer usually files the return and pays on completion day using money you send them in advance.